- 1Find a property or seize an opportunity
- 2Work out the finance and structure after
- 3Discover cash-flow pressure or a tax issue later
The property drives the plan.
Debt recycling is a way of restructuring your home loan so more of it starts working for you, instead of just costing you. This explains how it actually works, what it costs to run and how to tell whether it's likely to suit your situation.
The numbers behind the work
As featured in
It is a restructuring strategy, not a way of reducing what you owe.
If you have been paying down a mortgage for years, a large share of your repayments has gone into debt that is not earning you anything back. Debt recycling redirects that same effort into an asset that can pay you an income (such as rent) and may grow in value over time — while keeping a clear, documented record of what the borrowed money was used for, so the tax deduction stays valid if it is ever reviewed.
The catch is that you are still borrowing money to invest. If the investment does not perform well, you are left holding the debt without the payoff. The paperwork also matters from day one: the tax deduction depends on what the borrowed money was actually used for, not just which loan account it came out of. Get that record-keeping wrong and you could lose the deduction, even if everything else about the strategy was sound.
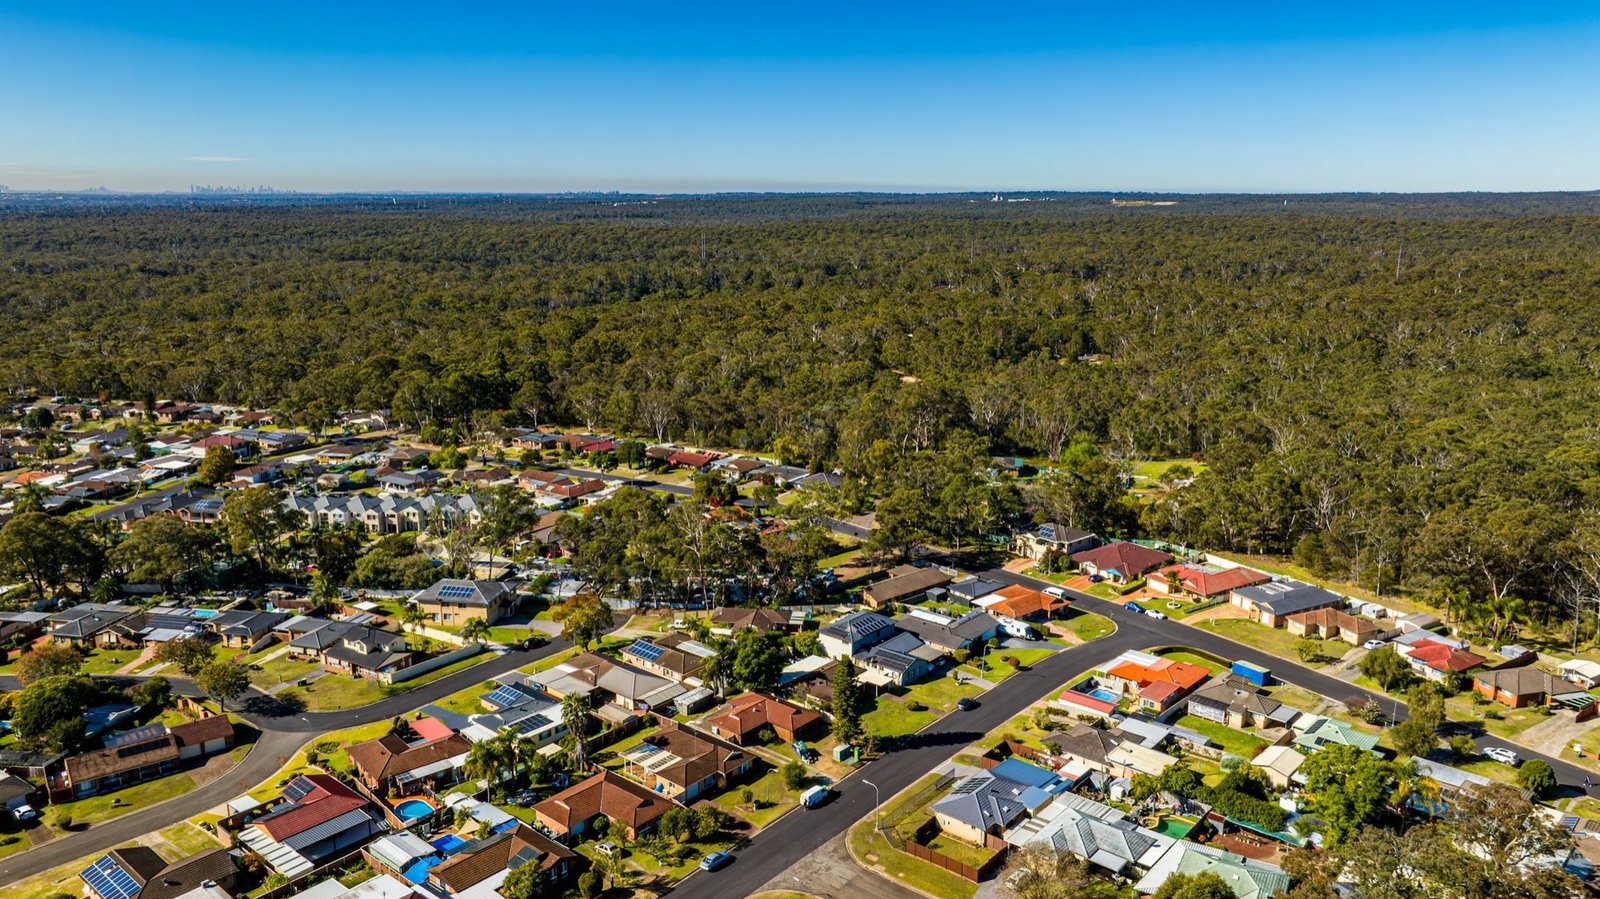
Imagine you own a $650,000 home with $250,000 still owing. That is roughly $400,000 in equity, on top of steady income and room in the budget.
A useful process does not start with a property. It starts with confirming the numbers, then works through the structure before any money moves.
There is no fixed equity threshold before debt recycling makes sense. How much you need depends on the purchase price, loan structure, lender, available equity, savings and the strategy used. A common assumption is that you need a 20% cash deposit plus costs, and that is often not the case.
Many clients Access Wealth works with start exploring property investment with roughly $90,000 to $110,000 available through cash, usable equity or a combination, sometimes less, depending on income, borrowing capacity and overall risk position. It is worth looking at the actual numbers before ruling it out.
A lender will not let you access all $400,000 of that equity — usually only a portion of it, kept below a set loan-to-value limit. For the homeowner above, that still comfortably covers the $90,000 used in the example below, the lower end of the typical starting range: redirecting $90,000 this cycle, against simply investing the same amount as cash.
The specialists involved depend on your position. Lending, tax and property are three different jobs, not one.
Total debt is $250,000 in every row above. Option 1 leaves it 100% private and adds $90,000 of new cash into the investment. Option 2 shifts $90,000 of the existing home loan to investment-purpose, without borrowing an extra dollar.
The risk is not simply a bad property. It is borrowing to invest before the interest-rate buffer, vacancy allowance, cash flow and paperwork are stress-tested and correctly set up. Get that order wrong and you find out about fees, conflicts or a stretched budget after the money has moved, not before.
The first three are managed by buying well, modelling conservatively and holding a buffer. The fourth is managed by involving a broker and an accountant before any money moves, not after. Debt recycling also tends to be the wrong move where cash flow already has no slack, income is about to change, the holding period would be short, or the only affordable property is a weak one.
Debt recycling touches three different professional lanes, and which ones you need depends on what you are investing in. Access Wealth's own lane is the property side: the strategy, research and acquisition behind the asset the debt is being recycled into.
Within that property lane, Access Wealth runs the same five-stage process for every client, so nothing falls through the gaps between strategy, finance and the purchase itself.
Clarify your goals, understand the resources you have to work with, and map the property pathway that may help close the gap.
Explore Plan →Validate the roadmap against your real finance position, connecting it with the lending, cash flow and safety net buffers needed to proceed with confidence.
Explore Protect →Research and shortlist properties against Access Wealth's own investment criteria to find the one that actually performs the role your strategy calls for, then coordinate the purchase.
Explore Acquire →Coordinate the contracts, deadlines, costs and inspections through to settlement and rent-ready handover, so nothing important is missed.
Explore Execute →Review the portfolio, update the roadmap, and identify the next sensible move as life and markets change.
Explore Grow →Yes. Debt recycling is a legitimate and widely used strategy in Australia. It works because the tax treatment of interest generally follows what the borrowed money is used for. Money borrowed to buy an income-producing asset can be deductible, while money used for your own home usually is not.
That is also why the setup matters so much. If investment and private money get mixed in the same loan, the deductible portion can become hard to prove, and the ATO can look closely at arrangements like that. Separate loan splits and a clean record of every redraw make it easy to show. Have a registered tax agent confirm your structure before any money moves. Access Wealth provides general information only, not tax advice.
There is no fixed number. What matters is how much of your equity a lender will actually let you access, which usually sits below a set loan-to-value limit, along with your borrowing capacity and how comfortably you can carry the repayments if rates rise.
Many clients Access Wealth works with start exploring property investment with roughly $90,000 to $110,000 available through cash, usable equity or a mix of both, sometimes less. If you already own a home, it is worth understanding how using equity to buy an investment property works and getting a lender to confirm your real position before ruling anything in or out.
Yes. The recycled funds can go into any income-producing asset, and property is one of the most common choices. The same rules apply: the loan used for the purchase needs to be kept separate from your home loan, and the property needs to be able to earn rent.
The property itself still has to stack up on its own. A weak asset bought with well-structured debt is still a weak asset. Access Wealth's role sits on the property side, researching and acquiring a property that can carry itself. It is worth knowing what a property investment advisor actually does before choosing who helps with that part. Where the strategy involves shares, funds or super instead, that needs an appropriately licensed financial adviser.
You are borrowing to invest, so the main risks come with that. If the investment performs poorly, you still carry the debt. A rate rise lifts your repayments on a larger effective exposure. Vacancy, maintenance or a drop in income can put pressure on cash flow.
There is also a structural risk. If the loan splits or paperwork are set up wrongly from day one, the tax treatment you were relying on may not hold. Most of this is managed by buying conservatively, stress-testing against higher rates and vacancy, keeping a buffer and involving a broker and accountant before you start, not after.
No, although they often turn up in the same plan. Debt recycling is about restructuring debt you already have, so more of it sits against an income-producing asset instead of your home. Negative gearing describes what happens when an investment costs more to hold each year than it earns, and how that loss may be treated for tax.
A debt-recycled property can be negatively geared, positively geared or neutral, depending on the rent, the loan and the costs. They answer different questions, so it helps to understand both before building either into a plan.
Start with a conversation — 15 minutes to talk through your goals and where you stand today. From there, our team helps you see what the first step toward building wealth through a property portfolio could actually look like. No pressure, no obligation. And if the timing isn't right, we'll tell you.