- 1Find a property you like
- 2Work out the finance after
- 3Discover the numbers do not work
The property drives the plan.
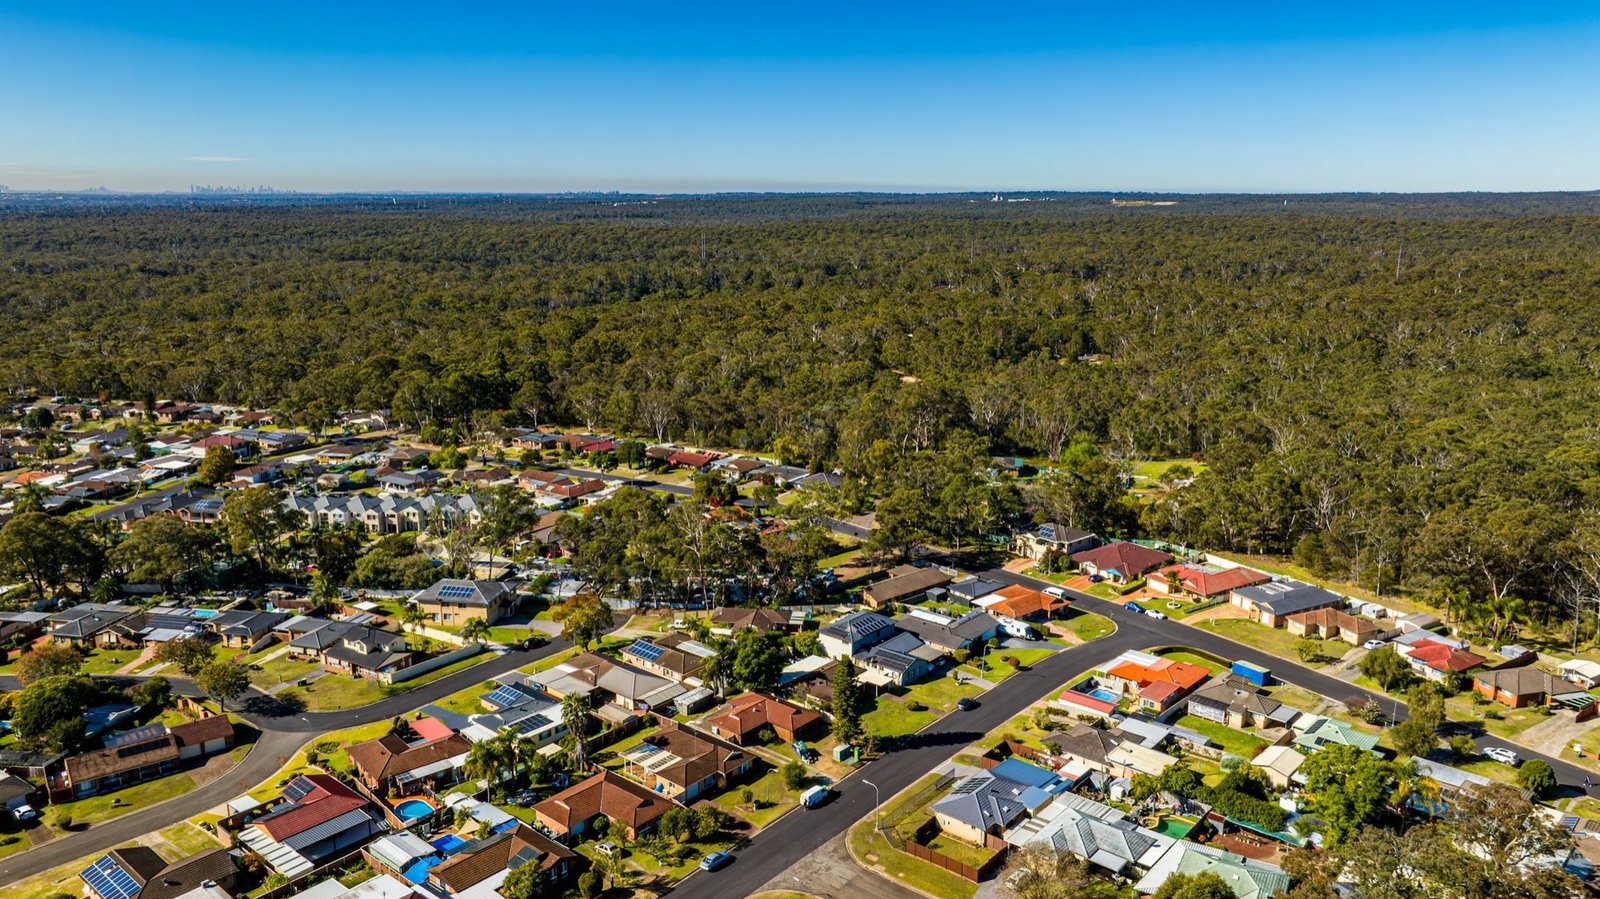
Most guides to buying your first investment property either oversimplify it or jump straight to picking a suburb. This walks through what actually has to happen first — your numbers, your borrowing position and the order those decisions come in — so you know whether now is the right time.
The numbers behind the work
As featured in
The order matters more than people expect. Confirming your borrowing position and setting your criteria before you start looking at properties means every option gets judged against the same yardstick, instead of falling in love with a property and hoping the numbers work out afterwards.
It is also a longer-term decision than it first looks — the number you start with needs to cover more than the deposit alone, which is worth breaking down properly.
There is no fixed amount you need before buying an investment property. How much you need depends on the purchase price, loan structure, lender, available equity, savings and the strategy used. A common assumption is that you need a 20% cash deposit plus costs, and that is often not the case.
Many clients Access Wealth works with start exploring their first investment property with roughly $90,000–$110,000 available (from cash, usable home equity, or a combination), though the exact requirement can be lower or higher depending on income, borrowing capacity, deposit source and overall risk profile. It is worth looking at the actual numbers before ruling it out.
Say you have $95,000 available, in the middle of that range. Here is what that figure typically needs to cover, not just the deposit.
Most of the risk in a first investment property shows up before the purchase, in the order decisions are made. Some of the recurring mistakes:
Finding your first investment property is one part of a bigger process. Access Wealth runs the same five-stage process for every client, working with the appropriately licensed lending and legal specialists so nothing falls through the gaps.
Clarify your goals, understand the resources you have to work with, and map the property pathway that may help close the gap.
Explore Plan →Validate the roadmap against your real finance position, connecting it with the lending, cash flow and safety net buffers needed to proceed with confidence.
Explore Protect →Research and shortlist properties against Access Wealth's own investment criteria to find the one that actually performs the role your strategy calls for, then coordinate the purchase.
Explore Acquire →Coordinate the contracts, deadlines, costs and inspections through to settlement and rent-ready handover, so nothing important is missed.
Explore Execute →Review the portfolio, update the roadmap, and identify the next sensible move as life and markets change.
Explore Grow →Here's what that looks like specifically when it comes to finding your first investment property — the acquire stage in detail:
Every shortlisted property is assessed against Access Wealth's own investment criteria — more than 20 checks across location, performance and quality. Some include:
Buying an investment property properly involves more than one type of professional. It is worth knowing where each one's role starts and ends:
Start with a conversation — 15 minutes to talk through your goals and where you stand today. From there, our team helps you see what the first step toward building wealth through a property portfolio could actually look like. No pressure, no obligation. And if the timing isn't right, we'll tell you.